LNG market in Q3 2026
Summary of events in Q3 2026
There is a temporary lull in Middle East again in the end of Q3. The pause in military operations at the beginning of the quarter and the resumption of shipments of Qatari and Emirati gas from Persian Gulf turned out to be temporary. The period of recovery was followed by a new round of attacks, and everything returned to sporadic voyages of gas carriers through Strait of Hormuz. The oil market trend of increased oil shipments through Strait of Hormuz using old shuttle tankers was not picked up by the LNG market: the impact of a UAV strike on an LNG carrier could be much greater than on an oil tanker.
As of now all underlying reasons to start the war are still active. Key reasons for suspension of military operations include inability to achieve military objectives with current arsenal, Trump's declining popularity ahead of November 2026 elections, and Iran's economic and financial challenges following the blockade of its maritime trade. The greatest damage was beared by Iran, Palestine, and Lebanon. The exporting countries (Iraq, Qatar, Kuwait, Saudi Arabia, UAE, and Bahrain) and importing countries (India, Pakistan, Japan, EU, and United Kingdom, as well as the countries of Southeast Asia) were economically affected as well. The initiators of the conflict have no interest in their fate or aspirations.
USA is making a lot of money by simultaneously increasing market prices and increasing the share of its energy exporters in global markets. The low price of the peaceful market is not beneficial to USA. The only strategic pain point for USA is financial impossibility of the countries they control from purchasing new US federal debt. Pyramid-shaped nature of US external national debt requires at least a trillion dollars per year in new money earned by foreign economies and transferred to USA.
LNG market has found a new temporary balance in Q3. US and other producers replaced isolated Qatari and Emirati LNG production capacities. Seasonally high LNG demand of Persian Gulf countries was met by Qatari and Emirati supplies. Low injection of natural gas into EU underground gas storages, coupled with a decline in demand in China and other Asian countries for expensive spot LNG supplies, led to a temporary stagnation in overall worldwide LNG demand. Spot prices for imported LNG remained high in importing countries, but did not reach a shock level.
As expected, EU continues to attack Russian LNG industry. Following its own rejection of LNG from Yamal, European Commission has predictably begun to “ban” transportation of Russian LNG. Greece has managed to obtain a temporary exclusion until 31.12.2027 for its shipping company, Dynagas, which operates ice-class Arc7 gas carriers specialized in exporting LNG from Russian Arctic projects.
As of 29.09.2026, there were 51 large and middle scale LNG plants with sea access in the world, including partially idle ones, with a total operational LNG liquefaction capacity of 473 MTPA. 9 plants were fully or partially idle with total non-operational capacity of 77 MTPA, including united LNG plant in Qatar and Das Island LNG in UAE.
In 2026, 26 MTPA of LNG capacity is expected to be commissioned. USA dominates this process - it will account for 52% in 2026. War in Middle East delayed Qatari and Emirati newbuilds.
USA remained to be number one supplier of LNG to the global market in Q3 2026. Australia is the second. Russia is the third.
In July, domestic natural gas consumption in Indonesia amounted to 145 mcm per day — a record since 2017. Given that production has been relatively stable since 2020, the growth in consumption is reducing amount of LNG available for export. LNG exports in July were the lowest since 2014 — only 28 mcm per day. Indonesia will lose a status of LNG exporter in a few years.
As of 29.09.2026, there were 224 regasification terminals in the world with total regasification capacity of 1137 MTPA.
Regasification capacities of 77 MTPA are expected to be commissioned in 2026 year. Y-o-Y growth is 6%. China’s share in capacity build up is 53%. Egypt, India, Honduras and Germany are in top 5.
China was the main importer of LNG in the world as result of Q3. Japan is the second. South Korea is the third.
On 03.12.2025, European Council and European Parliament decided to abandon import of Russian gas into EU. Pipeline gas supplies must stop no later than 30.09.2027, and in some cases before 01.11.2027. A transition period is provided for existing contracts. For short-term contracts signed before 17.06.2025, the ban took effect from 25.04.2026 for LNG and from 17.06.2026 for pipeline gas.
As of 29.09.2026, stocks of active natural gas in UGS of EU and UK amounted to 77.7 bcm. Stocks are significantly lower than in previous years. It is the lowest volume since 2021.
Egypt’s gas balance continues to change rapidly, and for the worse. In July, for the first time, domestic gas production accounted for less than half of domestic gas consumption: record demand (208 mcm per day) coincided with a record‑low production level (103 mcm per day). Now, Egypt’s population and industry are supplied with gas from the United States, Israel, and, in the near future, Cyprus. Egypt was importer #6 in Q3.
As of 29.09.2026, there were 874 operational linear LNG carriers with 63.9 MT of total cargo hold capacity. LNG carriers with 7.3 MT of total cargo hold capacity are expected to be commissioned in 2026. It will be all-time high value. Expected Y-o-Y increase is 16%.
High gas prices in importing countries have led to an increase in supplies and prices of thermal coal.
LNG plants
As of 29.09.2026, there were 51 large and middle scale LNG plants with sea access in the world, including partially idle ones, with a total operational LNG liquefaction capacity of 473 MTPA.
9 plants were completely or partially idle with a total non-functioning capacity of 77 MTPA. List of idle plants and trains:
All but one train of Qatari LNG plants. Most lines are idle (9) or destroyed (2). The plant operates at 20% of its pre‑war capacity (3 trains). In Seala, we consider the trains that were destroyed in March 2026 as closed, and we treat the projects officially named as repairs over a period of 3–5 years as a construction of new trains.
Adgas Das Island in UAE. Presumably complex keeps extracting and treating natural gas and supply it to UAE shore via undersea gas pipeline.
Marsa el Brega LNG in Libya.
Yemen LNG.
Train 1 at Atlantic LNG plant in Trinidad and Tobago. In January 2026, the train was closed by owners. Despite this Seala treats it as idle accounting for probable future Venezuelan supplies to revive it.
Train 2 at Arctic LNG 2 and Cryogaz-Vysotsk plant in Russia.
Trains C, D, E of the Botang LNG plant in Indonesia.
Train 2 of the Northwest Shelf LNG plant in Australia.
Damietta LNG plant and Egyptian LNG plants in Egypt. EGAS at Idku loads rare LNG cargoes from time to time.
Trains at 26 plants (including expansion projects for existing plants and debottlenecking projects) are under construction with new liquefaction capacity of 251 MTPA. Such an extremely high development rate for any industry indicates the upcoming changes in the industry in the coming years, which will be negative for LNG producers.
In 2026, 27 MTPA of LNG capacity is expected to be commissioned. USA dominates this process - it will account for 52% in 2026.
It is highly likely that starting in summer of 2028, LNG will be in relative surplus, which will lead to lower prices. These market conditions will allow USA to continue clearing the global LNG market of countries it dislikes - Russia, Iran (cross-border pipeline gas trade). US attention to Qatar is also likely to increase.
Loading
According to Seala AI, USA remained to be number one supplier of LNG to the global market in Q2 2026. Australia is the second. Qatar is out of Top 3 (8th place). Russia is the third for the first time.
USA
Commissioning of 6 MTPA Train 2 of Golden Pass was under way during Q3. First LNG is expected in December. The third train is expected to be commissioned in 2028. The plant is owned by ExxonMobil (30%) and QatarEnergy (70%).
Capacity optimization of 2.5 MTPA Elba Island LNG plant is underway. The process will be gradually completed by the end of 2027 and will add 400 kt per year to the LNG production capacity.
Construction of 1.64 MTPA Train 7 of Corpus Christi plant is scheduled to be completed in December.
Calcasieu Pass 2: First LNG is expected in the end of 2027 - in the beggining of 2028.
Q3 LNG shipments from USA amounted to 31.7 million tons at par with Q1 and Q2. Utilization of capacities existing by the end of the quarter exceeds 100%.
USA continues to successfully monetize the crisis in Eastern Europe started in 2013 under Biden administration (vice president in 2009-2017, president in 2021-2025) and consequent elimination of Russian energy resources from the European market. Commissioning of US LNG plants is synchronized with the disconnections of Europe from Russian gas and LNG. In the coming years, balancing of West of Suez gas market will be done y USA by limitation of export of remaining Russian pipeline gas and LNG.
Integrated gas market of EU and UK is dominant buyer of Q1 US LNG.
Egypt became the second largest buyer of Q2 US LNG resource with 1.8 million tons.
India became the third largest buyer of Q2 US LNG resource with 1.5 million tons.
USA supplied 1.3 million tons in Q2 to Caribbean countries (Panama, Dominican Republic, Jamaica, Colombia) excluding Puerto Rico.
Details of LNG shipment from USA are available at the link.
Canada
The main event in gas industry of Canada in Q3 was final investment decision on construction of the third and fourth trains of Canada LNG plant made on 29.09.2026. The capacity of each line is the same 7 MTPA. Launch is scheduled for the early 2030s. The shareholders are the same as for the first phase: Shell (UK and USA) – 40%, Petronas (Malaysia) – 25%, PetroChina (China) – 15%, Mitsubishi (Japan) – 15%, Korean Gas Company (South Korea) – 5%.
Two more local LNG plants are underway:
Woodfibre LNG plant near Vancouver with capacity of 2.1 MTPA.
Cedar FLNG plant next to Canada LNG with capacity of 3.3 MTPA.
Q3 LNG shipments from Canada amounted to 2.1 million tons.
Canada LNG is on the way to overcome technical difficulties affecting its core operations. In Q3 it is still not performing on the level of design capacity (1167 kt per month).
Q3 cargoes were delivered to East Asia and South-East Asia. Key buyers are South Korea, Japan and China (including Taiwan province).
Mexico
Construction of LNG facilities is under way in Mexico. All projects except New Fortress Altamira FLNG are located at West coast of Mexico and aimed at deliveries to Pacific countries.
Construction projects (Energia Costa Azul LNG, New Fortress Altamira FLNG) are delayed again.
3.25 MTPA Energia Costa Azul LNG sent the first cargo on 08.07.2026. Technical problems, identified after inspection of the first cargo production and loading, lead to some reworks. Commercial commissioning was shifted to Q4. 2.5 MTPA out of overall 3.25 MTPA is contracted by French TotalEnergies and Japanese Mitsui for 20 years. Start of deliveries under these contracts are expected in December 2026.
Completion of construction work on the second 1.4 MTPA train of New Fortress Altamira FLNG is expected to be completed in Q4 2026 and commercial operations are expected to begin in H1 2027.
Construction of Amigo LNG plant with a total capacity of 8.4 million tons per year will start soon.
Q3 loadings volumes amounted to 0.7 million tons.
Trinidad and Tobago
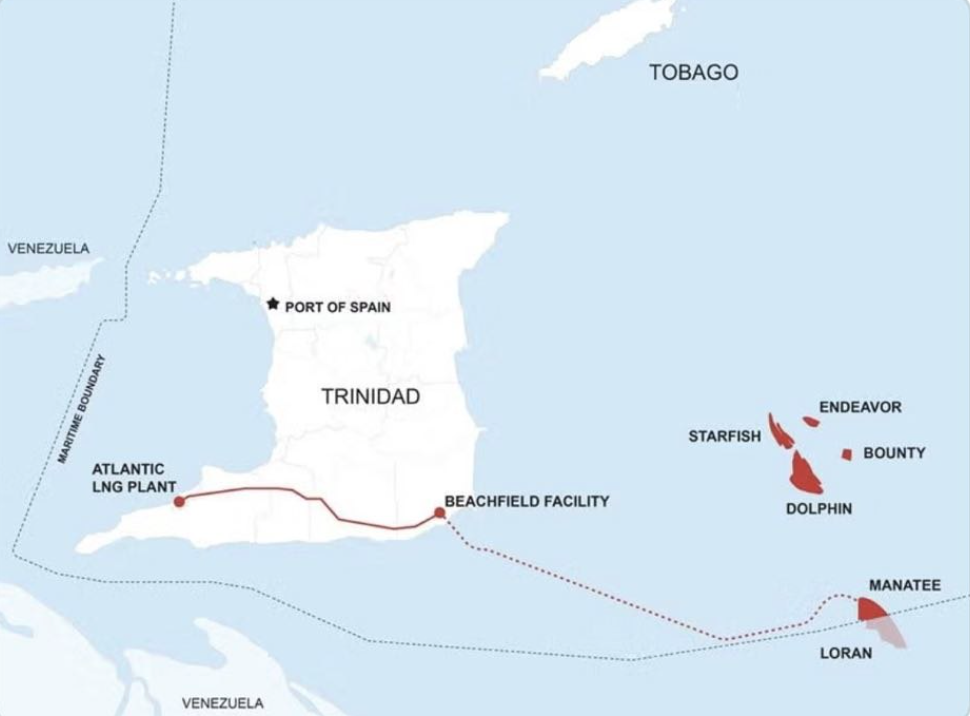
Q3 2026 LNG loadings amounted to 2.3 million tons. Utilization of operational capacities of the only LNG plant Atlantic LNG (11.8 MTPA without idle Train 1) - 78%.
Traditionally, LNG from Trinidad and Tobago is shipped worldwide and has a diversified customer base.
Chevron (USA) will hand over its license over Loran offshore gas field in Venezuela to Shell (UK and USA), which owns adjacent Manatee on Trinidad and Tobago side. It is definitely a step to revive production at Atlantic LNG plant and restart 3 MTPA Train 1.
Peru
Q3 loadings amounted to 1.0 MT.
Qatar
July 7 attack by an Iranian missile on Qatari gas carrier Al Rekayyat (IMO 9397339) off the coast of Oman became a symbol of the curtailment of LNG traffic through the Strait of Hormuz.
Q3 loadings at Ras Laffan amounted to 4.0 million tons. Almost all of Q2 LNG was unloaded at terminals in Persian Gulf, including Bahrain, Kuwait and UAE.
On 21.06.2026, an accident occurred at Barzan gas processing plant in Ras Laffan Industrial Plant. 13 workers were killed and 67 were injured. Production facilities were damaged.
As of Octobery Qatar faces the following consequences of the war:
Qatar will need at least two weeks after end of the war and opening of Strait of Hormuz to restore production at remaining 64.6 MTPA capacity of Ras Laffan. As the June accident has shown, actual timeline could be longer than 2 weeks.
12.5 MTPA of Ras Laffan capacity are heavily damaged and should be rebuilt, which will require 3-5 years. Although there are 46.8 MTPA capacities of under construction, which are scheduled to be delivered in 2027-2028. It will make up any decrease in Qatari production in mid-term.
Annual Qatari 2026 GDP will shrink by at least for 4% for each month of Strait of Hormuz closure.
QatarEnergy is compensatin loss of incumbent LNG supply in its international portfolio by US resource. Mainly by supply from its 18 MTPA Golden Pass LNG plant in USA (QatarEnergy’s share is 12.6 MTPA). It will compensate for destroyed capacity of its plant in Qatar.
Meanwhile QatarEnergy has extended force majeur clause in its contract with Italian Edison, Pakistani and Bangladesh companies.
Management of QatarEnergy has once again confirmed that there are no plans to build bypass gas pipelines in the direction of Turkey or EU.
Construction works of LNG expansion projects continue to be delayed — both due to the lack of a systemic solution for gas transportation through Strait of Hormuz and impossibility of safe delivery of equipment through the strait.
Details of Qatar's exports are available at the link.
UAE
The only LNG plant, Das Island (7.6 MTPA), has been mostly shut down since early March. Q3 LNG production amounted to 0.5 million tons.
The second LNG plant in the country, Ruwais, is expected to be launched in 2029. The plant's capacity will be 9.6 MTPA.
Discharge at regasification terminals in Jebel Ali and Abu Dhabi amounted to 1.1 million tons in Q2. Cargos came mostly from Qatar and also from UAE itself. Traditionally, discharges at these terminals peak in Q3 of each year during heat wave.
The country's largest gas processing plant, Habshan (63 BCMA), stopped operations on 03.04.2026, following an attack. On 16.04.2026, the plant began partial resuming of operations. This plant is critical for UAE's domestic gas market.
ADNOC has and continues to expand its own fleet of LNG carriers. As of 29.04.2026, the fleet has reached 13 LNG carriers. Two LNG carriers have been already added to the fleet in 2026: Al Taweelah (9972971) and Arada (9972969).
Details of Emirati gas market are available here.
Oman
Oman's only LNG plant Qalhat is located on the shores of the Gulf of Oman. The closure of the Strait of Hormuz did not affect shipments from this plant.
LNG loading volumes in Q3 amounted to 2.7 million tons. Plant’s utilization - 95%.
Majority of Q3 cargoes went to India and China. Omani LNG cargoes to India set the record - India is replacing Qatari LNG.
Australia
Gas balance
The first gas from Scarborough was received in July 2026. Launch of Pluto 2 is expected in Q4 2026.
LNG loadings
Q3 LNG loadings at Australian plants has grown compared to Q2 and amounted to 21.2 million tons. It corresponds to 100% utilization of operational capacities.
In Q2 2025 Australia traditionally became the number one LNG supplier to Japan and South Korea and regained number one in China.
Details of Australia's exports are available at the link.
Papua New Guinea
Q3 2026 loadings at the country's only 8.3 MTPA LNG plant amounted to 2.0 million tons. Utilization of the design capacity was 96%.
Almost all cargoes went to Japan and China (including Taiwan).
Pre-investment phase of a new LNG plant next to the existing one continues. The plant is planned to have three trains of 1.33 million tonnes of LNG per year each. Resource base is the Elk-Antelope field. Gas from the same field will also be liquefied at the existing plant under a tolling arrangement and exported in volumes of up to 2 million tonnes per year. The consortium developing the project comprises ExxonMobil (operator, USA) 34.1 %, Kumul Petroleum and MRDC (Papua New Guinea) 22.5 %, Santos (Australia) 21 %, TotalEnergies (France) 20 % and ENEOS Xplora (Japan) 2.4 %.
Brunei
Q3 2026 loadings at the only LNG plant (7.2 MTPA) amounted to 1.2 million tons.
All Q3 cargoes went to neighboring East Asian countries - Japan, Taiwan, South Korea and others.
Indonesia
In July, domestic natural gas consumption in Indonesia amounted to 145 mcm per day — the third‑highest average monthly consumption over the entire period and a record since 2017. Given that production has been relatively stable since 2020, the growth in consumption is reducing amount of LNG available for export. LNG exports in July were the lowest since 2014 — only 28 mcm per day.
Loadings at Indonesian LNG plants amounted to 3.7 million tons in Q2.
Discharge of domestic Q2 LNG at own regasification terminals amounted to 1.5 million tons (40% of the country's production).
China (including Taiwan), South Korea and Japan are key external consumers of Indonesian LNG.
In Q2, 2.4 million tons were discharged at Indonesian regasification terminals, which is a record value. Of these, 1.5 million tons were unloaded from Indonesian LNG plants.
Malaysia
Q3 LNG loadings at Malaysian plants decreased compared to Q2 and amounted to 6.8 million tons. Utilization of the design capacity (32 MTPA) was 85%.
Deliveries of Malaysian LNG to domestic regas terminals amounted to 533 kt (7% of domestic LNG production).
LNG discharges at two Malaysian regas terminals (Pengerang LNG, Melaka FSRU) amounted to 1.8 million tons in Q2. Australia and Malaysia itself are leading suppliers.
In Q2 2026, a regas project of Gas Malaysia (GASM) jointly with Tokyo Gas (Japan) and VTTI (Netherlands and UAE), was legally established. FSRU will be based near Yan in Kedah state. The terminal will have a capacity of 6 MTPA. This project reflects growing domestic gas consumption trend in the country, as well as Tokyo Gas's strategy to expand its sales portfolio in Southeast Asia.
Details of Malaysia's exports are available at the link.
Russia
In Q3 Ukraine, US, EU and UK continued to attack Russian gas supplies to the global gas market:
08.07.2026 — Drones attacked Krasnodarskaya compressor station, which feeds gas into Blue Stream pipeline to Turkey and into domestic Dzhubga — Lazarevskoye — Sochi pipeline.
24.08.2026 — Drones attacked Astrakhan gas processing plant.
09.09.2026 — Drones attacked Novy Urengoy condensate treatment plant.
LNG plants loadings
Q3 LNG loading at the plants amounted to 6.8 million tons. 1.1 million tons were loaded on transhipment hubs (mostly at Kildin island STS zone and floating storages Saam and Koryak).
3.1 million tons were shipped from Yamal LNG (Sabetta port). China was the largest buyer. France is the second.
2.1 million tons were loaded at Sakhalin-2 (Prigorodnoye port). Сargoes went to Japan, China and South Korea.
Per Seala AI data, Q2 loadings from Arctic LNG 2 amounted to record 1.3 million tons. In September, two power plant modules for the second train of the plant were shipped from Zhangjiagang, China.
Medium-tonnage plant Gazprom LNG Portovaya loaded 225 kt. All went to China.
Cryogaz-Vysotsk has been idle in Q3.
Domestic market
Wholesale and retail prices for natural gas on Russian market continue to rise. Price of gas on SPIMEX in October (MTD) is breaking a record.
October increase in retail tariffs for gas for all type of consumers, including population, will amount to 9.6% starting from October 1, 2026, according to a resolution of Government of Russian Federation. Gas transportation tariffs have increased even more significantly — by 11.6%. This is the second increase this year. Starting from January 1, 2026, tariffs have already been indexed by 1.7%, which was due to an increase in VAT rate.
Gas in Russia is still relatively cheap if compared to major economies, but its ruble and USD value continues to rise steadily. The loss of EU market has led to permanent increases in domestic gas tariffs to balance Gazprom’s revenues — previously, gas sales to EU accounted for majority of Gazprom’s net profit and effectively kept gas tariffs for domestic consumers at low levels.
More over, in the coming years, share of hard-to-recover gas fields in the structure of production at new gas fields is expected to grow, which will also lead to an increase in the cost of gas production and the selling price.
Details of Russian gas market are available at the link.
Norway
Q3 2026 loadings at the country's only large-tonnage plant Hammerfest Snøhvit (4.2 MTPA) amounted to 1.4 million tons. Almost all cargoes went to EU and UK.
Mozambique
Q3 2026 loadings at the only LNG plant Coral South (3.4 MTPA) amounted to 0.8 million tons.
LNG from Mozambique is supplied to wide list of countries. Asian countries dominate among the recipients.
Western energy companies keep developing new LNG projects in Mozambique.
The country's second Coral North floating LNG plant with a planned capacity of 3.4 MTPA is expected to be commissioned at the end of 2027. Owners of both Coral projects are Italian Eni, US ExxonMobil, Chinese CNPC, Korean Gas Corporation of South Korea, UAE’s ADNOC and local Empresa Nacional de Hidrocarbonetos. Mozambique's share in these projects is 10%. LNG sales of ENH’s 10% share are controlled exclusively by Dutch Vitol.
French TotalEnergies keeps development of Mozambique LNG Zone 1, onshore project with 13 MTPA capacity, after lifting force majeure in October 2025. Meanwhile TotalEnergies demands compensation from Government of Mozambique in the amount of 4.5 billion USD for the delay in the implementation of the project.
ExxonMobil’s Rovuma LNG (18 MTPA) project is still awaiting of FID. Final investment decision is expected in the end of 2026, but have good changes to be postponed further.
Thus potential Mozambique’s liquefaction capacity is up to 38 MTPA. It could make Mozambique one of the leader of LNG industry.
Details of Mozambique's LNG industry are available at the link.
Angola
LNG exports from Angola amounted to 0.8 million tons in Q3. The 5.2 MTPA plant’s utilization - 62%. Supplies are stable.
India consumed more than half of Q3 resource.
Previously, Angola LNG's main resource was associated gas from offshore oil platforms.
Increase in gas production at depleted Sankha oil field has provided 2.3 mcm per day (0.8 bcm per year) of additional resource for Angola LNG in 2025. At the second stage of production improvement at this field, additional supplies to the LNG plant are expected in the amount of 6 mcm per day (2.2 bcm per year).
Natural decline in oil production led to a decrease in the associated gas resource for the LNG plant. New gas consortium plans to add up to 12 mcm of gas for the LNG plant from the second stage of Quiluma and Maboqueiro gas fields, which will ensure full utilization of the plant and make its expansion feasible.
Republic of the Congo
There are two FLNG in the country: 0.6 MTPA Tango FLNG and 2.4 MTPA Nguya FLNG. Plants are owned by Italian ENI (65%), Russian Lukoil (25%) and domestic SNPC (10%) with production sharing approach.
Q3 loadings amounted to record-breaking 0.6 million tons.
Equatorial Guinea
Punta Europa LNG plant (3.7 MTPA) continues stable shipments. Q3 loading amounted to 0.5 million tons.
Cameroon
Q3 loadings amounted to 139 kt at the Cameroon FLNG.
Hilli Episeyo (7382720), which is the basis of this LNG plant, will finish its work in Cameroon in December 2026 and will be moved to Argentina for a new FLNG project.
Nigeria
Volume of loadings at Nigeria's only LNG plant in Q3 amounted to 4.8 million tons at par with record-breaking Q1 and Q2. Utilization of design capacity (22.2 MTPA) - 87%. Most of the cargo went to India, Portugal and China.
Nigeria continues to actively increase its exports of natural gas in the form of urea. In 2025, exports amounted to 3.4 million tons, which is equivalent to 1.7 million tons of LNG (11% of LNG production in 2025). The increase in urea exports over the past four years is 2.6 times.
Preliminary construction work has begun on a gas pipeline from Warri in Nigeria to Hassi R'Mel in Algeria. Commissioning is expected in the early 2030s. The pipeline's capacity will be 30 BCMA (82 mcm per day). At the same time, Niger (at least 1 BCMA) and Algeria will take part of the gas as a transit fee.
Mauritania and Senegal
Q3 2026 at Greater Tortue Ahmeyim FLNG loadings amounted to 0.7 million tons. It shows that Greater Tortue Ahmeyim FLNG reached its designed 2.5 MTPA capacity.
Algeria
Domestic demand keeps increasing. Algeria exports majority of gas to export via pipelines.
Loadings at the country's two LNG plants amounted to 1.7 million tons in Q3 2026. Utilization of design capacity (25.5 MTPA) - 27%
EU, Türkiye and UK have consumed all Q2 Algerian LNG.
Details of Algerian exports are available at the link.
Regasification terminals
As of 29.09.2026, there were 224 regasification terminals in the world with total regasification capacity of 1137 MTPA.
Regasification capacities of 77 MTPA are expected to be commissioned in 2026 year. Y-o-Y growth is 6%. China’s share in capacity build up is 53%. Egypt, India, Honduras and Germany are in top 5.
Discharge
According to Seala AI Terminal, China was the main importer of LNG in the world as result of Q3. Japan is the second. South Korea is the third.
China
Gas balance
The spring decline in LNG imports had little effect on China's overall gas balance: consumption, production and pipeline gas imports stayed within their usual ranges. Pipeline gas imports are traditionally high in summer, as the heating season ends in Central Asia.
LNG infrastructure
China continues to dominate in regas capacity newbuild. China continues to rely on its gas infrastructure and actively develop it. China is flexible in LNG purchases - balancing is carried out by pipeline gas, coal, and hydroelectric power plants.
PipeChina LNG terminal in Longkou is going to be commissioned during Summer 2026. Capacity of the first stage of the terminal will be 5 MTPA. This terminal will be expected to become the second entry point for blacklisted Russian LNG. Thus, this gas terminal follows the market strategy of Shandong oil terminals, which are specifically focused at import of crude oil from countries blacklisted by the West (Iran, Russia, and previously Venezuela).
2026 is expected to be a record year for the commissioning of regasification terminals in China - 41 MTPA. Although many projects scheduled to go online this year, had previously been delayed. Probably only a portion of regasification terminals under construction will be completed de facto.
There is already some regional surplus of regas capacity. It led and keeps leading to low utilization levels for new and existing terminals.
LNG import
LNG deliveries to China amounted to 16.8 million tons in Q3. LNG import mostly rebounded since May, but still below pre-war volumes.
Q3 LNG imports in Taiwan province amounted to 6.6 million tons. Utilization of the regas terminals (20.0 MTPA) was 132%. LNG import volumes have been relatively stable for a long time and slowly growing with overall GDP growth.
Israeli-US war against Iran led to halt of Qatari LNG supplies to China since the end of March. Namely Qatar became the leading supplier of LNG to China in 2025. In Q2, China increased its purchases of Australian, Russian and Malaysian LNG. Russia is China's second-largest LNG supplier after Australia.
LNG re-export
In Q2, China re-exported only 2 cargoes - 120 kt. In Q1 re-export amounted to record-breaking 19 cargoes (1.3 million tons of LNG).
Details of Chinese gas market are available here.
Japan
In Q3, Japan imported 14.8 million tons.
Qatar and UAE are not major LNG suppliers in Japan. Three-quarters of LNG import are based on long-term contracts and oil-indexed formula prices. Japanese import has not suffered due to the closure of Strait of Hormuz. However, due to mechanics of price formulas increase in oil prices will affect cost of LNG import in 2026.
Japanese government continues to successfully obtain “permits” from Trump to import Russian LNG from Sakhalin-2.
South Korea
Q3 LNG import amounted to 10.3 million tons. In line with seasonal norms.
Singapore
LNG deliveries to Singapore in Q3 amounted to 1.2 million tons.
Details of the import and re-export of LNG by Singapore are available at the link.
Thailand
Q3 LNG imports amounted to 2.9 million tons. Utilization of the terminals (19 MTPA) was 61%.
Gas-fired TPPs account for more than half of power generation in Thailand. Therefore, LNG demand strongly depends on seasonality of electricity demand and availability of cheaper sources of electricity (primarily hydroelectric power plants).
The period from March to May is the peak period in terms of electricity demand.
India
Q2 LNG imports amounted to 6.6 million tons. This is at the level of Q2-Q3 of previous years. Indian gas demand peaks in summer. As we see, there is no physical shortage of LNG in India. In March, due to stoppage of Qatari LNG, there was a decrease in LNG imports, which was compensated in April. April LNG imports reached a record high.
Qatar became the leading supplier of LNG to India in 2025 (11.8 million tons). UAE, which is also off the market, was the second leading supplier (2.9 million tons).
In Q2, USA became the leading supplier to India for the first time, with a volume of 1.8 million tons, setting a new record for the country. USA has effectively replaced Qatar and UAE as a supplier to India.
Nigeria came in second place with a volume of 1.5 million tons, also setting a new record for the country.
Oman came in third place with a volume of 1.3 million tons, also setting a new record.
Heavy dependence on Qatar in LPG and LNG import led to significant energy crisis in the country. This affects cooking processes of hundreds of millions of poor and low-income Indians. Energy crisis in India deepened in Q2 due to blockade of Strait of Hormuz and the Iranian coast by USA. India could easily import Russian LNG and LPG at any time with short notice - everything depends on Modi’s desire to execute sovereign energy policy.
On top of that, it will affect domestic fertilizer production. We consider that there is a huge destruction of demand from Indian fertilizer producers at the 1000-1200 USD per thousand cubic meters level. Which in turn will lead to lower crops this and next season. In case of prolonged blockade of Strait of Hormuz prices for locally produced food (starting with wheat) will skyrocket this autumn.
LNG itself accounts for half of India's natural gas market (the rest is locally produced gas). India's energy system is predominantly coal-based and can withstand reduced gas supplies. However, simultaneous market crisis in LNG, LPG, and oil supplies, coupled with rising energy import prices, places immense pressure on India's financial system. Rupee's exchange rate is currently being artificially maintained through burning of Indian gold and foreign currency reserves. Prolonged war in Middle East will inevitably lead to a weakening of rupee and further increases in energy import prices denominated in rupees. All of this leads to a collapse in domestic gas demand, primarily among domestic fertilizer producers.
In Q2, Indian government initiated a coal gasification program. It is planned to process about 75 million tons of coal per year into gas. This is equivalent to 8% of the country's coal production. India is the second largest country in the world (after China) in terms of coal production and consumption. Design capacity of synthetic methane production is 15 billion cubic meters per year, which is equivalent to 43% of the country's natural gas production. Estimated investments in the project are 135 bAED / 250 bCNY / 3.5 tINR / 2.7 tRUR (in equivalent).
Pakistan
Q3 LNG imports amounted to 565 kt, at par with Q2. Severe problem with LNG import with suitable for Pakistan price continues.
Qatar provided almost 100% of LNG imports to Pakistan. At the same time, Pakistan faced the problem of excess supplies due to stagnation of domestic gas market. In recent years, Pakistan has cancelled a lot of Qatari LNG cargoes due to oversupply even under pre-war price levels. In March the problem became the opposite - Pakistan is forced to find all the necessary import volume on spot (!) market. As the result March 2026 discharges shrank. This will create crisis conditions for poor Pakistani gas market.
Kuwait
Since July, Kuwait has restored production to pre‑war levels. LNG consumption and imports have returned to seasonal norms.
Q3 discharge volume amounted to 1.2 million tons.
Egypt
Egypt’s gas balance continues to change rapidly, and for the worse. In July, for the first time, domestic gas production accounted for less than half of domestic gas consumption: record demand (208 mcm per day) coincided with a record‑low production level (103 mcm per day).
Now, Egypt’s population and industry are supplied with gas from USA, Israel, and, in the near future, Cyprus.
On 28.07.2026, final investment decision was made for Сronos upstream project in offshore Cyprus. Owners of the field are: Eni (operator, Italy) – 50%, TotalEnergies (France) – 50%. Gas from Cronos field will be supplied to infrastructure of Egyptian Zohr and then sent to Damietta LNG plant. Eni owns 50% of the shares in this plant. It is expected that LNG from the plant will be shipped to EU countries. The first deliveries will take place in 2028.
Q3 discharge amounted to 4.1 million tons. It is record value. Egypt became importer number 6 in Q3. USA dominates in Egyptian LNG import - 3.6 million tons.
Türkiye
During summer months, gas consumption in Türkiye is at its seasonal low, which results in minimal demand for LNG — the most expensive of the gas resources.
Q3 discharge amounted to mere 628 kt. Traditionally, Türkiye actively imports LNG during the cold months from November to March.
Türkiye has expressed desire to extend a contract with Iran for supply of Iranian natural gas, expiring in the end of July. The contract volume is 10 BCMA. Actual supply in 2025 was 7.7 BCM.
Details of Turkish gas market are available here.
EU and UK
Planned tax on external imports of natural gas
European Commission plans to introduce another tax on external import of resources to EU - Methane Regulation (Regulation (EU) 2024/1787). Official wording is based on methane emissions at its production. Transportation and regasification segments and foreign upstream projects controlled by EU companies will be excluded from the tax. De facto, this is a hidden taxation of gas supplies from USA, Qatar, Algeria, and Azerbaijan.
In December 2025, European Commission proposed to US LNG exporters procedural easing of “audit” of gas fields. US Chamber of Commerce once again rejected both the procedural relief and the entire initiative, as US government basically does not want to pay any tax on its LNG.
Despite all of Trump's threats to limit LNG supplies to EU in case EU does not give up on political and economic controversies with USA, no one seriously believes these threats. US State Department has spent decades methodically building EU's energy dependence on USA and eliminating Russian energy supplies, and no one there wants to voluntarily give them up, when they won.
Gas stocks at UGS
As of 29.09.2026, stocks of active natural gas in UGS of EU and UK amounted to 77.7 bcm.
Gas reserves in UGS in the middle of injection campaign are at a low seasonal level. After challenging gas winters of 2021-2022 and 2022-2023, there has been a relaxation in the minds of gas company executives, which is reflected in gradual decrease in volume of gas injected. EU market has become more decentralized and spot-based.
Q2 2026 EU natural gas futures market was in a backwardation and did not provide market incentives to buy gas now and incur additional storage and financing costs. Everyone is waiting for the opening of Hormuz, resumption of Qatari LNG production, and a decrease in market prices.
Heating season lasted from 17.11.2025 to 02.04.2026.
Net gas injection into UGS in Q2 amounted to 14.9 bcm. This is the lowest value for all summer quarters in history.
Given backwardation of gas futures market, it is unprofitable for private gas companies to buy gas now, store it, pay interest on a trade loan, and then resell it cheaper. Lack of commercial stimulus will lead to reduced volumes of LNG purchases for injection into UGS facilities - injection will be carried out only under pressure from European Commission and national authorities.
LNG import
Q3 discharges of external LNG amounted to 21.4 million tons.
Top LNG importers in Q3:
Netherlands - 3.5 million tons.
Italy - 3.4.
Spain - 3.2.
France - 3.2.
Germany - 1.9.
UK traditionally is out of the largest importers list in Q2-Q3. The country imports LNG only during periods of high demand for natural gas due to lack of significant UGS capacity.
In Q3, USA has increased its market share in EU and UK to record-breaking 64%. Trump's position is to increase US share up to 100% as new LNG projects are launched in USA and put EU and UK under full energy dependence on US energy supplies. European Commission accepted risk of complete energy dependence on USA and even started standoff with Qatar and planned complete abandonment of Russian gas import. Presumably next growth of US LNG share is scheduled for Q1 2027 at expense of Yamal LNG.
Russia took the second place in Q2 with 1.7 million tons and market share in the amount of 8%. Russia supply LNG to EU only from Yamal. Yamal LNG is traditionally taken by 4 countries - Spain, France, Belgium and Netherlands. Other EU countries are avoiding Yamal LNG even in time of gas crisis. On 03.12.2025 European Council and European Parliament decided to limit EU countries from possibility to import Russian pipeline gas and LNG. LNG supplies under current short-term contracts signed before 17.06.2025 are “allowed” until 25.04.2026.
Nigeria came in third place with volume of 1.5 million tons and 7% market share.
Details of LNG imports by EU countries are available at the link.
Ukraine
Gas reserves at UGS as of 29.09.2026 amounts to 11.1 bcm, which is close the highest in SVO era. Injection campaign has been completed.
All gas purchases are financed by EU and Norway in the form of direct or indirect loans and grants. EU funding comes from supranational European Commission, with all costs ultimately borne by taxpayers. Norway finances Ukrainian gas supply de facto from additional revenue it receives from exporting gas and oil to EU at inflated prices due to Ukraine.
Almost all molecules of natural gas imported by Ukraine comes from Texas and Louisiana.
Fleet
Current fleet
As of 29.09.2026, there were 874 operational linear LNG carriers with 63.9 MT of total cargo hold capacity.
Newbuild
LNG carriers with 7.3 MT of total cargo hold capacity are expected to be commissioned in 2026. It will be all-time high value. Expected Y-o-Y increase is 16%.
South Korea is the leader in LNG shipbuilding. Japan, historic leader in the construction of gas carriers, systematically stopped their construction for internal economic reasons. South Korea has won this competition and currently dominates among existing fleet and among LNG vessels under construction.
China pursues South Korea, moving from building relatively cheap oil tankers and bulk carriers to building much more expensive LNG carriers. China is the number two shipbuilder of LNG carriers right now with a dynamically growing market share. Prospects of Chinese shipbuilding are limitless.
18.06.2026 new Arc7 ice-class LNG carrier Konstantin Posyet (9904704) was delivered by SSK Zvezda. In addition, two new LNG carriers Petr Stolypin (9904675) and Sergey Witte (9904687) are expected to be completed by Zvezda shipyard in 2026.
Market view for Q4 2026
Primary natural gas consumption will grow in Q4 and reach its peak in December. EU and, to some extent, East Asian countries have deferred gas demand from last gas summer — this increases expected gas demand in Q4 above seasonal norms. At the same time, accumulated gas stocks in key LNG import markets will certainly be sufficient for Q4 demand, and all weather‑related risks, if any, will be realised in Q1 2027.
Key expected event in Q4 is resumption in November of US and Israeli attacks on Iran and, likely, Yemen. This will lead to a temporary escalation in Middle East and further reduce LNG supply.
Our base scenario is that the Strait of Hormuz will be mostly shut and status quo remains. Under this scenario we forecast spot prices of LNG in ports of importing countries at level 1000+ USD per thousand cubic meters. We think that in some period of winter time (probably in December) spot prices will temporarily touch 1200 USD per thousand cubic meters level.
We consider that there is a huge demand destruction at the 1000-1200 USD per thousand cubic meters level, including buying LNG fo storing in EU UGS, Indian chemical companies, spot Japanese, Chinese and South Korean purchases.
Notes:
Join Seala AI’s Linkedin page to be informed of all new future releases with new dashboards and insights.
Non-mainstream oil and gas news and views are available in Seala AI’s telegram channel.
Full set of reports for each country and much more information are available via Seala AI terminal.